Commercial Roof Insurance Claim Assistance in Greensboro, NC
A commercial roof insurance claim in Greensboro moves faster when the damage is documented before the adjuster's visit, not explained afterward. We inspect the roof, record what we find, and build a scope that matches the actual condition.
Request A Roof Walk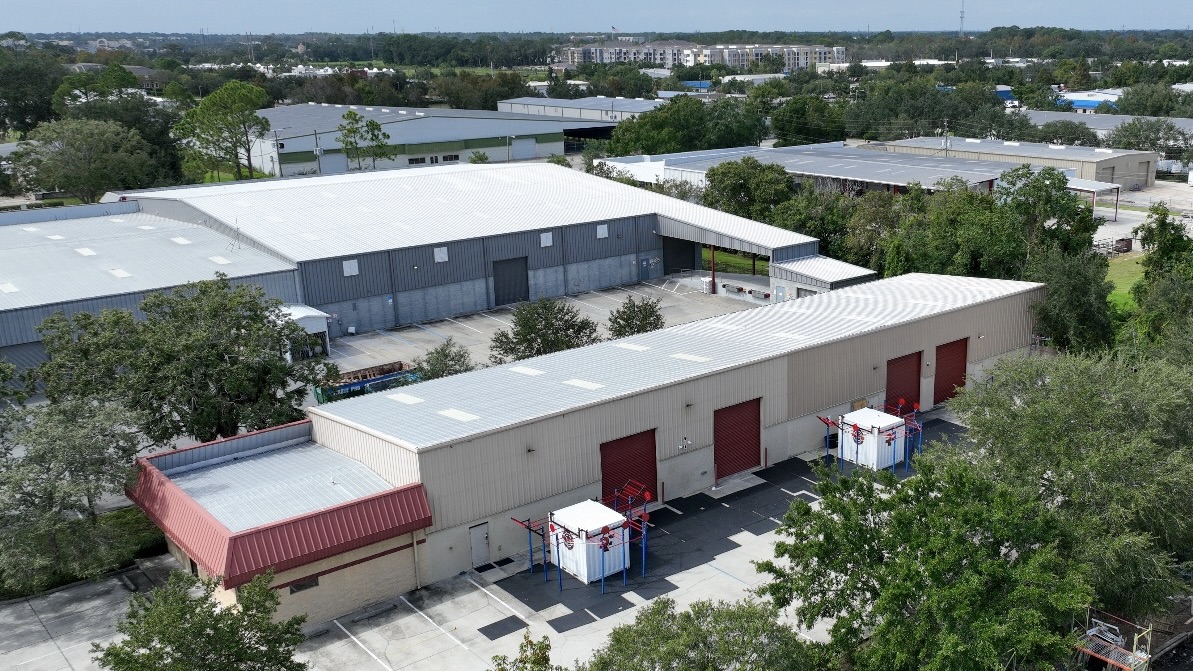
Most commercial roof claims start the same way: a leak shows up inside the building, or a roofer notices hail bruising or a lifted membrane seam during a routine check. What decides whether the claim moves cleanly from there is the quality of the roof file behind it. We document the damage with dated photographs, measurements of the affected roof area, moisture readings where water may have tracked under the membrane, and a written account of what we found and where we found it. That file becomes the basis for a repair or replacement scope an adjuster can evaluate against the roof's actual condition, not a guess made from the ground.
Greensboro's commercial roof stock reflects the city's manufacturing and logistics history. Converted textile and furniture-era buildings around downtown and South Elm Street often carry older decking and multiple roof layers, which changes how a claim gets evaluated once the tear-off starts and hidden layers are exposed. Newer distribution and warehouse roofs along the Piedmont Triad International Airport corridor, where FedEx operates a regional hub alongside Honda Aircraft Company, HAECO Americas, and Cessna, tend to be large single-membrane systems where wind uplift and ponding water are the more common claim triggers. We read the roof for what it actually is before we write the scope, not from a standard template.
Meeting the adjuster on the roof
When an adjuster is assigned to a commercial roof claim, we walk the roof with them whenever the schedule allows it. We point to the specific damage, explain what caused it, and show the parts of the roof an adjuster might not think to check on their own: edge metal, pitch pockets, curb flashing, drain bowls, and rooftop unit curbs. We are not there to negotiate coverage or argue the claim. We are there to make sure the scope reflects everything the roof actually needs, including code-required upgrades that come with a repair or replacement under North Carolina's adopted building code, and matching requirements when a discontinued membrane color or metal profile can't be patched invisibly.
Timing matters too. Most commercial property policies set a window for reporting damage, and insurers generally respond better to a claim filed close to the event than one reported months later after the condition has worsened on its own. If you're not sure whether something you're seeing is worth a claim, an inspection costs you the time it takes to walk the roof, and it either gives you documentation to file with or tells you the issue is routine maintenance, not storm damage.
When a claim comes back denied or underpaid
A denied or underpaid claim is usually a documentation gap, not a bad-faith decision. If an adjuster's scope leaves out damaged insulation, skips a section of membrane with hail bruising, or prices a patch where the roof needs a tear-off, we go back to the roof, gather the missing evidence, and put it in writing. That might mean a second set of photos, a moisture map, or a manufacturer opinion on whether the existing membrane can still be repaired or needs to come off. We hand that documentation to the owner to bring back to the insurer or their public adjuster; negotiating the claim itself stays outside our role.
Repair, or full-scope replacement
Not every hail mark or lifted seam means the whole roof has to come off. We separate cosmetic damage from damage that affects performance, and we say so in the file. When the damage is limited to a section, we scope a repair. When the membrane is compromised across enough of the roof, or the deck has taken on water, we document why a full-scope replacement is the more defensible number, including code-required insulation upgrades and drainage corrections the existing roof may be missing.
What to have ready before scheduling a roof walk
Before we schedule an inspection, it helps to have the building address, the approximate roof age if known, any interior leak photos already taken, and a contact who can grant roof access. If a claim number has already been assigned, we note it in our file so our documentation lines up with the insurer's records from the start. For properties with a facility manager or a management company handling multiple sites, we're used to working through that layer as well; the roof file stays sorted by building regardless of how many people are copied on the correspondence.
We're your roofing contractor, not a public adjuster. We inspect, document, and build an accurate damage scope so you and your insurance adjuster are working from the same facts. Filing and negotiating the claim itself stays with you or your adjuster.
Does insurance cover commercial roof replacement?
It depends on the cause of loss and your policy's terms. Wind, hail, and other covered perils are often included, but coverage, deductibles, and depreciation schedules vary by policy. We document the roof condition and cause of damage; your insurance agent or adjuster can confirm what your specific policy covers.
What does the roof documentation process look like?
We start with a full roof inspection and photograph every area of damage, take measurements, and check for moisture intrusion under the membrane. That becomes a written scope you can submit with your claim, and we're available to walk the roof with your adjuster when they schedule their inspection.
What if the adjuster's scope missed damage we can see?
We go back to the roof, document the missed area with photos and measurements, and provide an updated scope you can submit as supplemental evidence. Appealing or negotiating with the insurer stays with you or your public adjuster.
How do you decide between repair and full replacement in a claim?
We look at how much roof area is affected, whether the deck or insulation took on water, and whether the existing membrane or metal system can still be matched for a repair. The scope we write states the evidence behind that recommendation.
Do you file the insurance claim for us?
No. Filing and negotiating the claim is between you, your insurance company, and your public adjuster if you have one. We document the roof and build the repair or replacement scope that supports your claim.